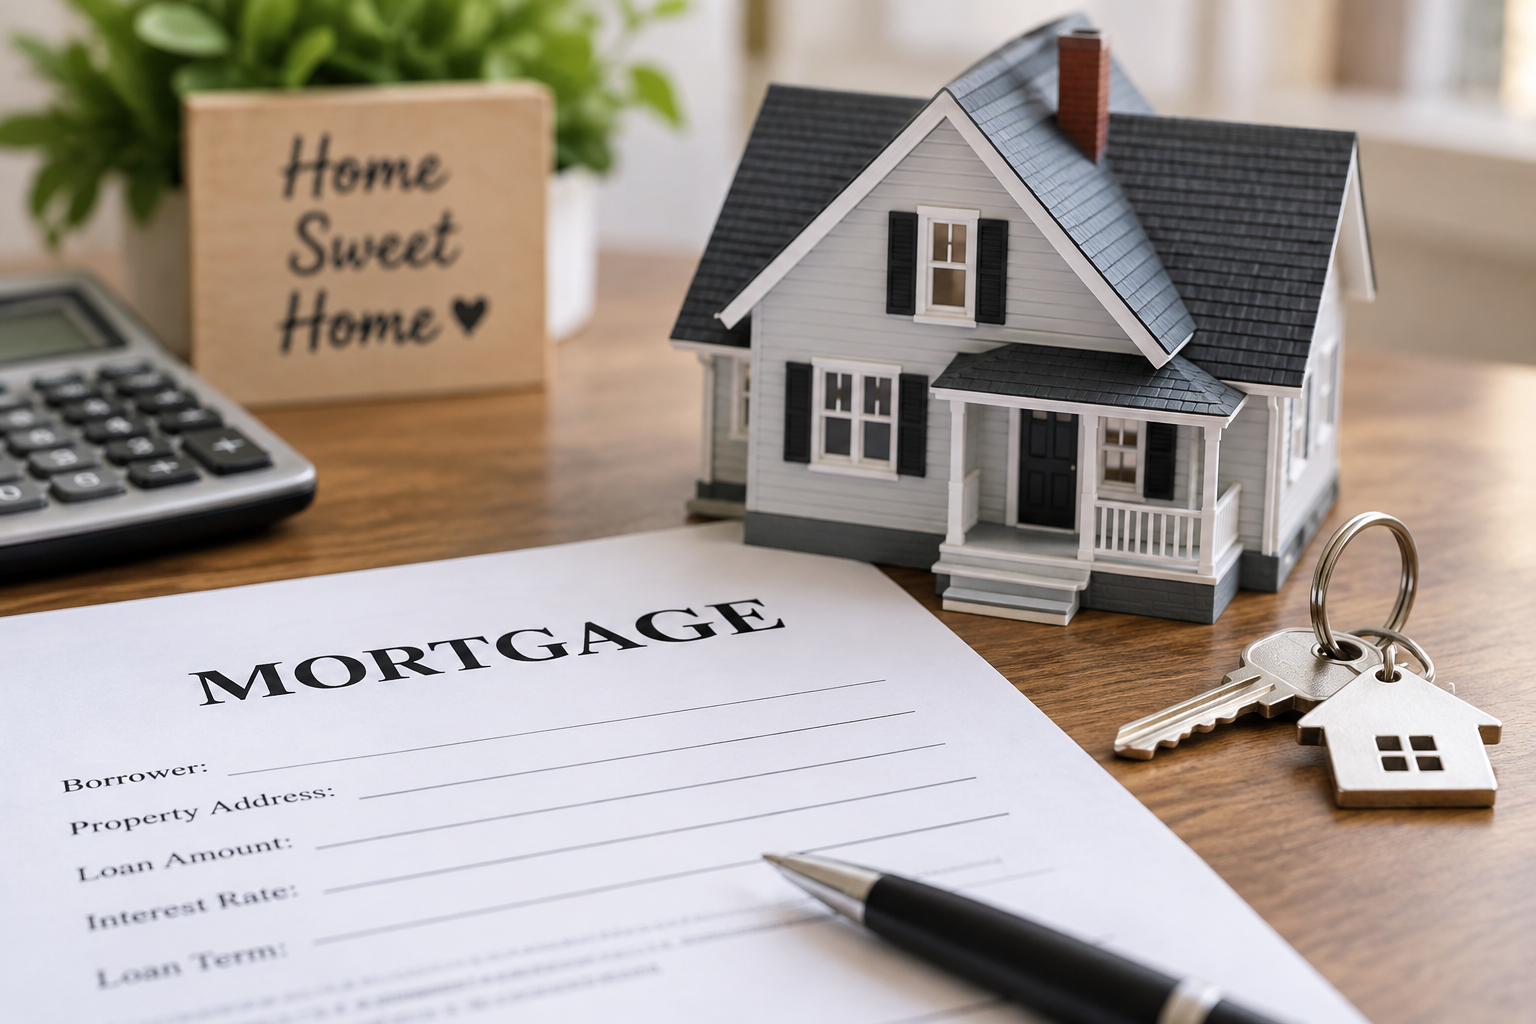
A mortgage renewal notice can seem like routine paperwork. Yet the end of a mortgage term presents an important opportunity to reassess your borrowing arrangements. Rather than automatically accepting the first offer, reviewing your Renewal Mortgage options can help ensure your financing continues to reflect your current circumstances.
Your income, household expenses, property equity, and financial priorities may have changed since your previous mortgage agreement began.
Understanding the Mortgage Renewal Process
Most Canadian mortgages have a contractual term that is shorter than the full amortization period.
When the term ends, an outstanding balance generally remains. The borrower must then arrange financing for the next term or repay the amount owing.
Renewal Versus Refinancing
Renewal generally involves continuing the outstanding mortgage balance under a new term and applicable conditions.
Refinancing involves replacing or restructuring the mortgage, potentially changing the balance, amortization, or other important features.
Understanding the distinction can help borrowers identify which process suits their objectives.
Begin Reviewing Your Mortgage Before Maturity
Waiting until the final weeks of a mortgage term can limit your opportunity to compare alternatives.
Start by reviewing the maturity date, remaining principal, interest rate, payment frequency, and available renewal conditions.
Examine Your Current Financial Position
Consider whether your household income has changed.
Have you taken on additional debts? Are major expenses approaching? Do you anticipate retirement, relocation, or a change in employment?
These questions can influence the Renewal Mortgage structure that best suits your situation.
Review Your Long-Term Housing Plans
Someone planning to sell a property soon may value different mortgage conditions from someone intending to remain for many years.
Portability and early repayment provisions can be particularly relevant when relocation is possible.
Important Mortgage Features to Compare
Interest rates are important, but they should not dominate every renewal decision.
Fixed and Variable Interest Options
Fixed-rate arrangements provide interest-rate certainty during the term.
Variable-rate arrangements introduce exposure to changes in the applicable interest benchmark.
Evaluate both possibilities against your budget and tolerance for changing borrowing costs.
Prepayment Flexibility
Some mortgage agreements allow additional principal payments within specified limits.
These privileges may be useful for borrowers expecting occasional bonuses, irregular income, or other available funds.
Early Termination Conditions
Ending a mortgage before maturity can trigger penalties.
Review how these charges are calculated and whether the mortgage conditions align with your future plans.
Should You Stay or Explore Other Lending Options?
Existing borrowers may receive a renewal offer without completing an entirely new mortgage application.
However, that convenience should not replace a thoughtful comparison.
Moving to another lender can involve eligibility assessments, documentation, and possible administrative expenses.
A Renewal Mortgage decision should reflect the complete financial arrangement rather than one attractive feature.
Common Renewal Mistakes
Accepting an offer without reviewing the conditions is a frequent oversight.
Other mistakes include overlooking prepayment restrictions, failing to prepare for higher payments, and assuming that every mortgage term provides identical flexibility.
Reviewing local mortgage renewal guidance can help homeowners prepare questions before committing to another term.
Plan for Payment Changes
If your new interest rate differs from your previous rate, your regular payment or amortization outcome may change.
Calculate the effect on household cash flow before finalizing the agreement.
Create a Renewal Checklist
Confirm your maturity date, review outstanding debt, update your household budget, and examine competing mortgage structures.
Ask for written clarification of unfamiliar conditions.
Keep copies of important correspondence and ensure the final agreement reflects the terms you intended to accept.
Conclusion
A Renewal Mortgage is more than an administrative step. It is a chance to reconsider affordability, repayment flexibility, and future housing plans.
By preparing early, reviewing contractual conditions, and comparing suitable alternatives, homeowners can approach renewal with a clearer understanding of their choices.
A carefully selected mortgage term can support financial stability while preserving flexibility for life’s next chapter.
What do you feel about this post?
Like
Love
Happy
Haha
Sad